

Buying a UAE Home as an Expat: Resident and Non-Resident Mortgage Checks
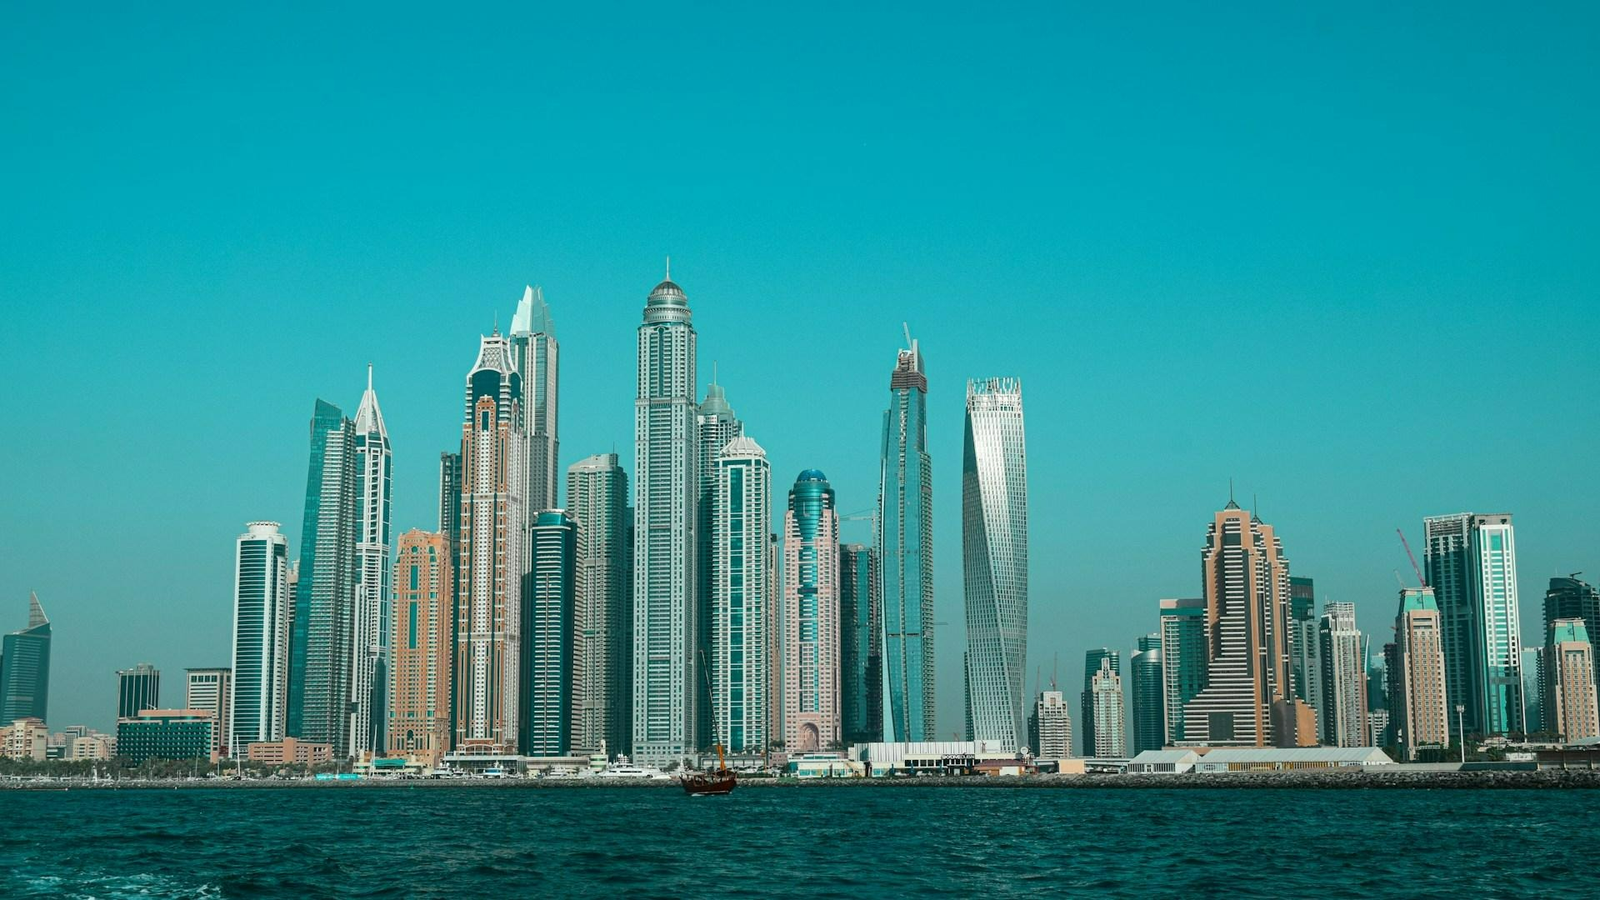
Two buyers can choose similar apartments in Dubai and arrive at very different mortgage budgets. One lives and works in the UAE; the other earns overseas and plans to buy a home here. The property price may be identical, but the lender still needs to understand each buyer's income, commitments and available cash.
Before comparing headline rates, establish which type of application you are making. A useful starting budget has three parts: the cash needed to complete the purchase, a manageable monthly payment, and money left over after moving in.
Start with your residency and income profile
UAE residency and the source of your income are separate questions. An employee receiving a local salary, a resident business owner and a buyer living abroad can require different supporting evidence. Describe your circumstances accurately from the beginning, including whether income is earned in dirhams or another currency.
Non-resident mortgages are available, but eligibility is specific to the lender. HSBC, for example, offers a route for qualifying Premier and Private Bank customers buying from outside the UAE. That is a bank-specific option, rather than evidence that every overseas buyer qualifies.
Avoid assuming that an advertised maximum borrowing percentage applies to your circumstances. Ask whether the lender accepts your residency profile, income source and intended property before treating a quotation as part of your budget.
For a starting checklist, Masarif's UAE expat mortgage guide brings together resident and non-resident considerations, including documentation and overseas income.
Separate the deposit from the complete cash budget
Loan-to-value, usually shortened to LTV, describes the loan amount as a proportion of the property's value. It is useful for understanding the deposit, but it does not tell you everything needed to complete a purchase.
Consider a purely illustrative AED 1.5 million property. If the agreed mortgage were AED 1.05 million, the buyer would need AED 450,000 towards the purchase price. That is 70% financing. These figures explain the calculation; they are not an available bank offer or a lending limit.
Transaction costs sit outside that example. They can include lender arrangement and valuation fees, property and mortgage registration costs, and any applicable broker or legal charges. Insurance and moving expenses also belong in the plan.
Build a simple cash schedule showing each amount and when it is due. Keep an emergency reserve separate. A budget that uses every dirham at completion leaves little room for a repair or a delay in receiving income.
Organise evidence before comparing applications
Document preparation is easier when it follows the way you earn money. For a salaried application, gather identification, evidence of employment and the statements showing salary receipts. Emirates NBD's published expatriate mortgage checklist, for example, includes a passport and Emirates ID, a salary certificate and six months of bank statements.
Self-employed applicants need to explain the business as well as personal finances. The same bank lists company ownership documents and audited financial statements among its requirements. A business balance is not automatically the same as regular personal income.
For an overseas application, obtain the lender's specific document list before arranging translations or certification. Ask which income records it accepts and how it handles your income currency. Keep a record of these answers so that two lenders' quotations can be compared on the same assumptions.
Prepare a clear explanation of unusual account movements. A one-off receipt, a transfer between your own accounts and recurring earnings should be easy to distinguish.
Test affordability against your actual household spending
A lender's affordability assessment and your own comfort level serve different purposes. The UAE Central Bank's mortgage framework requires lenders to consider repayment capacity, including other debt commitments, employment security and living expenditure. A property's value alone does not settle whether the borrower can manage the loan.
Your household calculation should also leave space for ordinary spending: transport, school costs, family commitments and savings. Include ownership expenses such as service charges, maintenance and insurance when comparing buying with renting.
Run the numbers using a less favourable scenario as well as the initial quotation. Consider a higher payment, reduced variable income or a period when a property earns no rent.
For someone earning outside the UAE, add a currency scenario. If fewer dirhams can be bought with the same overseas salary, the mortgage may absorb more of that income. This is a planning exercise, not a prediction about exchange rates.
Read beyond the introductory rate
Two quotations are only comparable when the loan amount, term and assumptions match. A lower initial rate can look attractive while leaving questions about later payments or fees unanswered.
Where a product has an introductory fixed period, identify what happens when it ends. For an EIBOR-linked product, check the reference period, the bank's margin and when the rate is reviewed. HSBC's published variable-rate explanation illustrates how changes in the benchmark can affect monthly payments.
Read the Key Facts Statement and compare arrangement charges, insurance requirements, early settlement and partial repayment terms. Record any conditions attached to the quoted pricing.
If you may sell, relocate or make a substantial extra repayment, include that scenario in the comparison. The most useful quotation explains what happens during the period you realistically expect to hold the loan.
Treat pre-approval as a stage in the process
An approval in principle can help establish a sensible price range before serious property negotiations. It is based on an initial assessment; HSBC explicitly distinguishes it from a guaranteed home loan.
Keep track of its expiry date and outstanding conditions. The lender still needs to complete the required checks and approve the final transaction. Its valuation is also a separate assessment from the seller's asking price.
Before committing to purchase deadlines, establish what remains outstanding and how a financing delay would be handled. Keep the payment schedule, mortgage conditions and transaction documents together so that a date in one document is not overlooked when reading another.
Bring a complete picture to the comparison
Create a one-page buyer brief containing your residency status, income sources, existing commitments, available cash, preferred property type and target monthly budget. Use the same brief for each lender.
Record unresolved questions beside each quotation instead of filling the gaps with assumptions. That makes it easier to see whether an attractive rate is actually available to you, whether the cash requirement is manageable, and which application is ready to move forward.